
First-Time Buyer Programs in Shasta County: What the City Line Changes
Redding's median sale price was $399,735 in August 2026, up 3.7% from a year earlier. For most first-time buyers, the harder number is the cash needed at closing.
Shasta County has three separate programs aimed at that gap, and which ones you can use depends first on which side of the Redding city limit the house sits.
Why the Address Decides Your Options in Shasta County
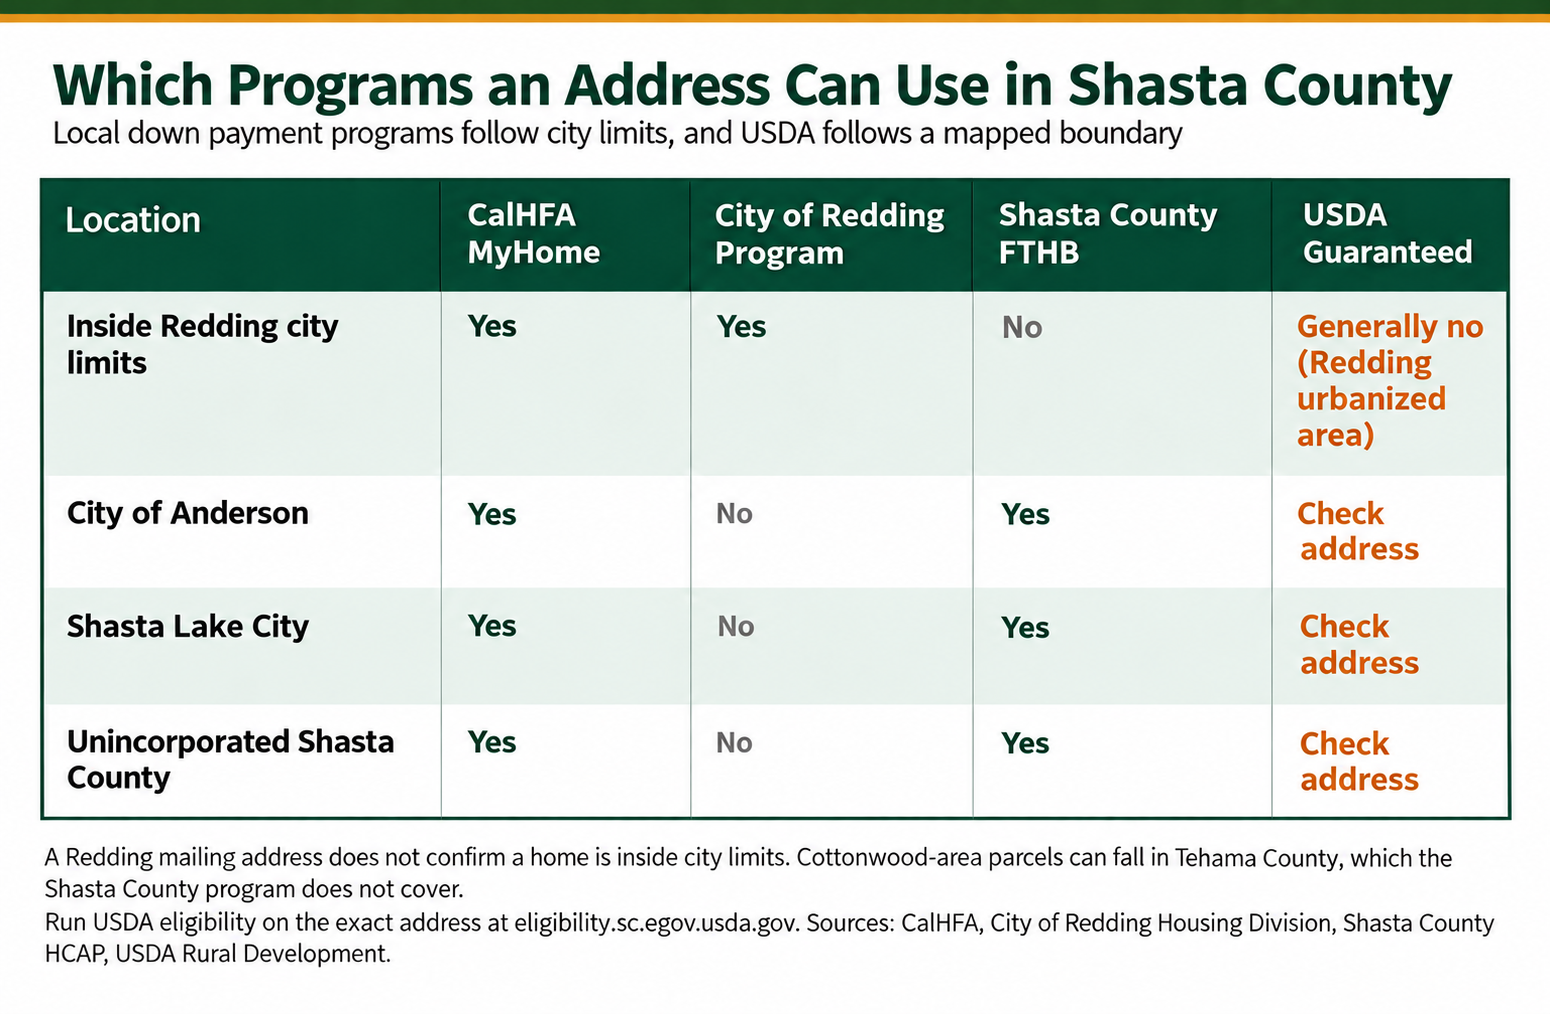
Down payment help here comes from three levels of government, and each draws its own map. The state program through CalHFA works countywide. The City of Redding and Shasta County each run a local loan, and their service areas do not overlap.
Inside Redding City Limits
A home inside the city limits can qualify for the City of Redding Homebuyer Program and for CalHFA MyHome. It cannot use the county program, which sends Redding buyers to the city.
USDA financing is generally off the table too, because USDA's eligibility map excludes the Redding urbanized area.
Anderson, Shasta Lake City, and Unincorporated Shasta County
Shasta County's First Time Home Buyer Program covers the unincorporated county plus the cities of Anderson and Shasta Lake City. That includes communities such as Palo Cedro, Cottonwood, Bella Vista, and Shingletown.
CalHFA MyHome works here as well, and USDA eligibility is possible across much of this area, address by address.
Addresses Near a Boundary
Mailing addresses follow postal routes, not city limits, so a Redding address alone does not confirm a home is inside the city. Cottonwood-area parcels can also fall on either side of the Shasta and Tehama county line, and the Shasta County program only covers Shasta.
Confirm jurisdiction on the specific parcel before you plan around a program. Most first-time buyers who ask us about assistance have not checked this yet, and it changes the whole list.
CalHFA MyHome Anywhere in Shasta County
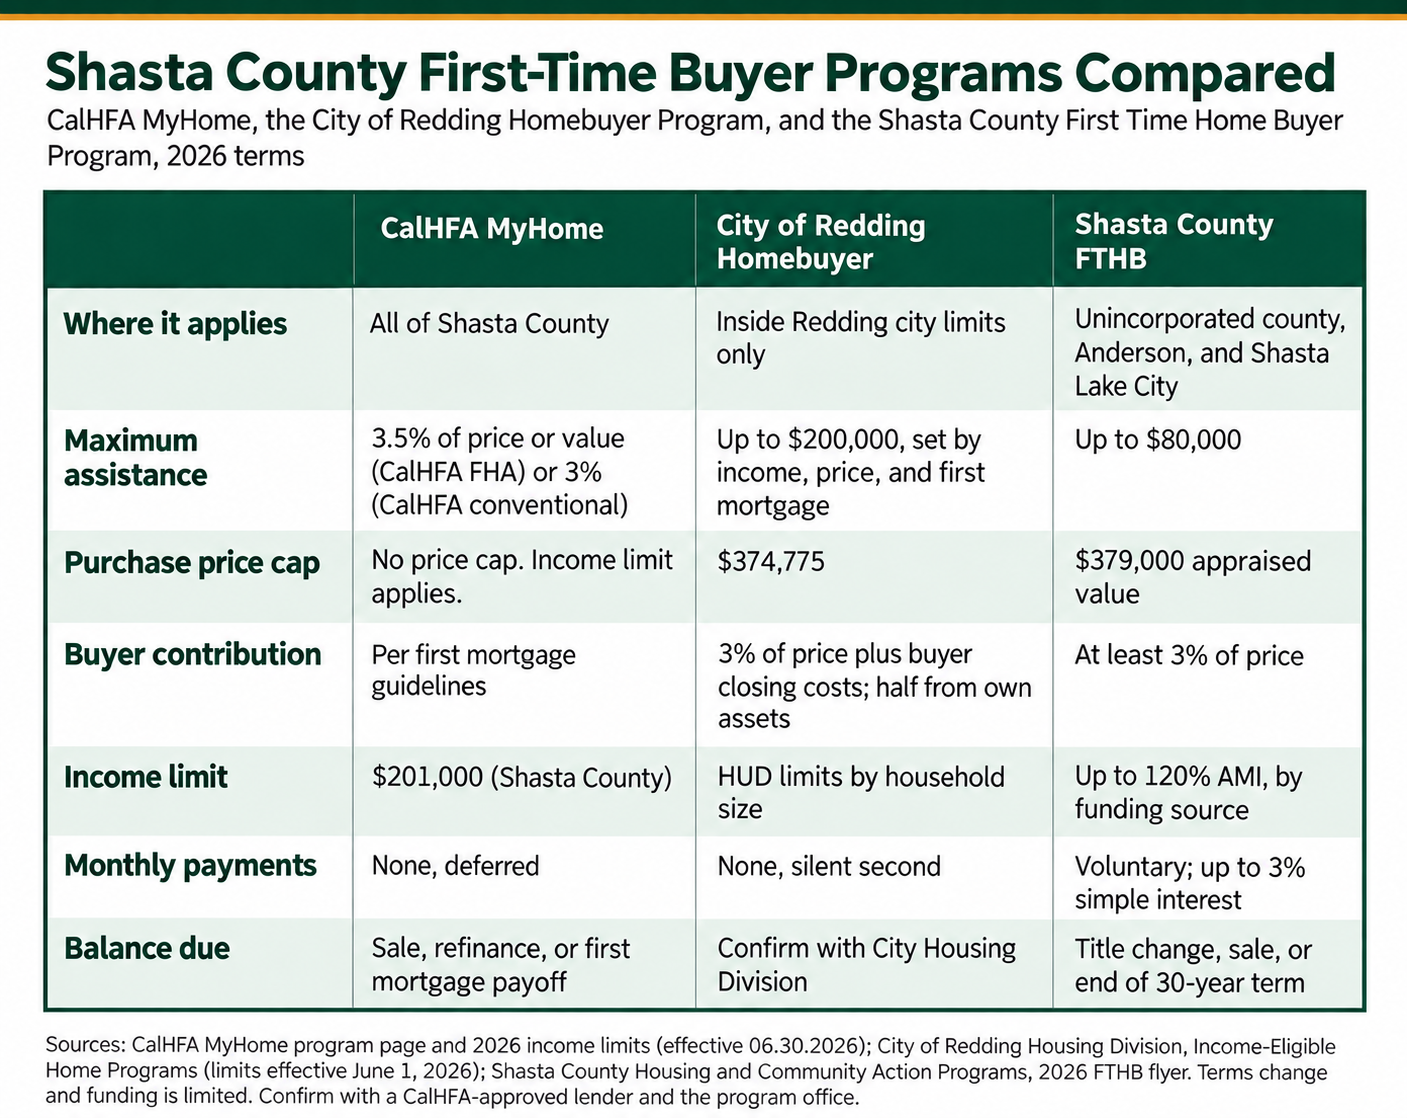
MyHome is the state layer and the only one of the three that works on both sides of the city line. It is a deferred-payment junior loan of up to 3.5% of the price or appraised value, whichever is less, on a CalHFA FHA first mortgage, or up to 3% on a CalHFA conventional first mortgage.
The money can go toward the down payment, closing costs, or both. CalHFA does not lend directly, so you apply through a CalHFA-approved loan officer, and MyHome only comes paired with a CalHFA first mortgage.
Who Qualifies
You need to meet CalHFA's first-time homebuyer definition, live in the home as your primary residence, and stay under CalHFA's income limit. Non-occupant co-borrowers are not allowed, so a relative cannot co-sign from another address.
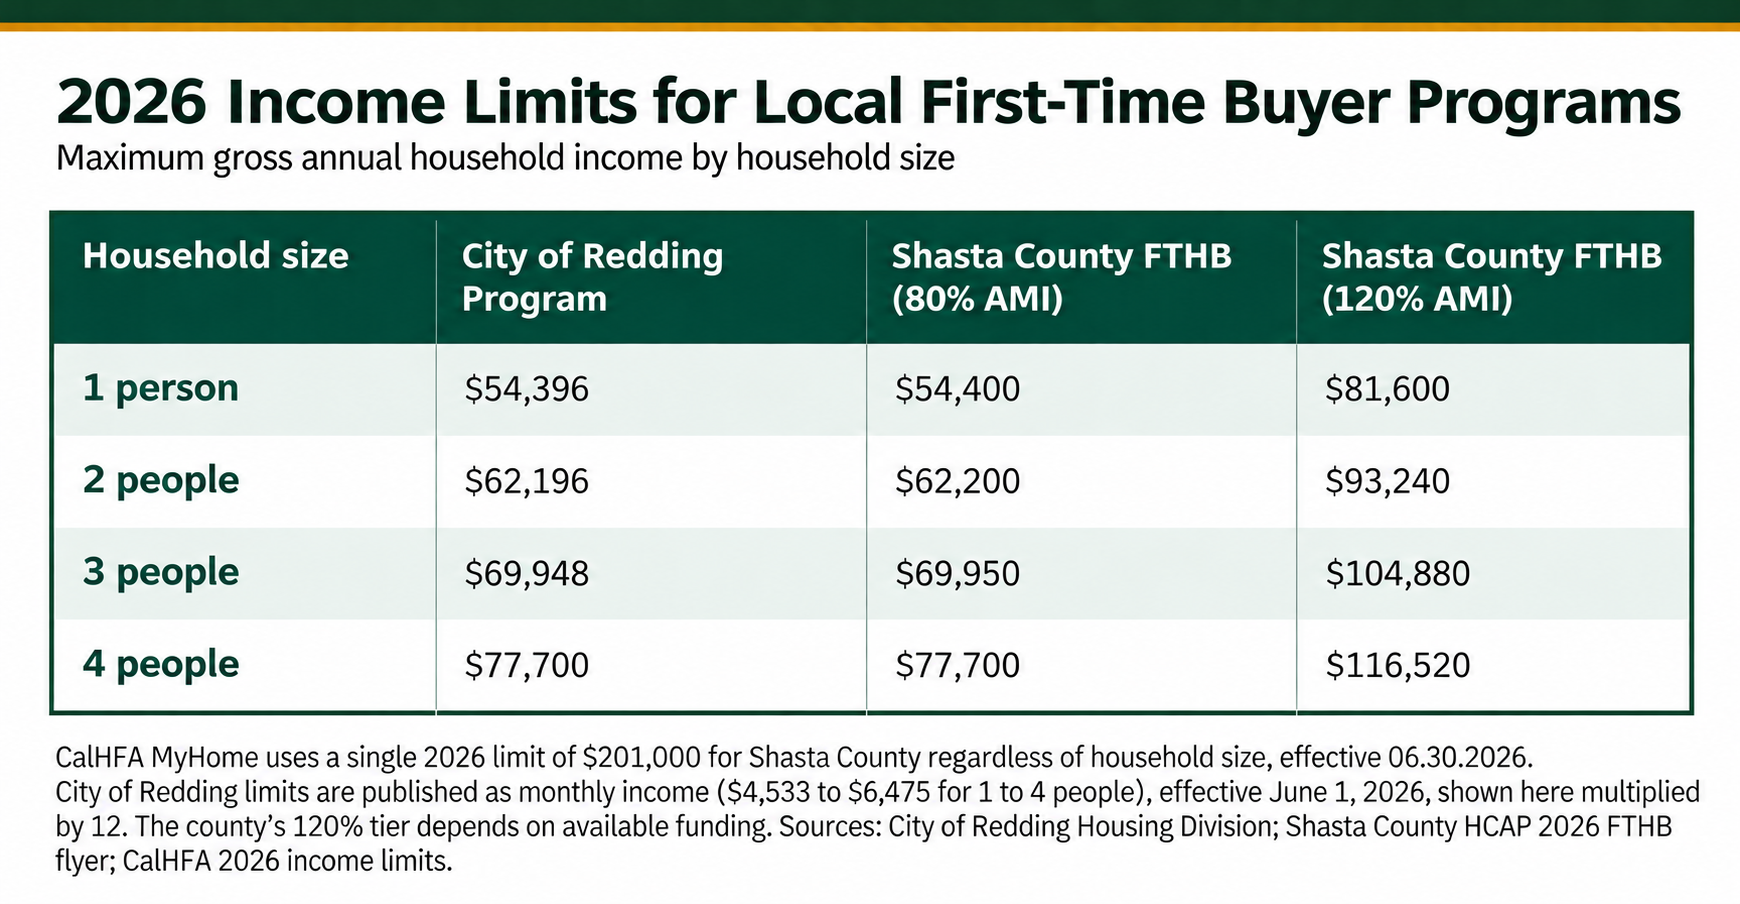
For Shasta County, the 2026 limit is $201,000, effective June 30, 2026. CalHFA limits income rather than purchase price.
Eligible properties include single-family homes, approved condos and PUDs, and manufactured housing, and a guest house or in-law unit on the lot may be eligible.
The Homebuyer Education Requirement
One occupying first-time borrower on the loan must complete homebuyer education and counseling.
The only online course CalHFA accepts is eHome's eight-hour course, which costs $100 and includes a one-on-one counseling follow-up.
The alternative is a live course, in person or virtual, through NeighborWorks America or any HUD-approved housing counseling agency.
We usually find that buyers who finish the course before they start touring move faster when the right home comes up.
How Repayment Works
Payments on MyHome are deferred. Nothing is due until the home is sold, refinanced, or the first mortgage is paid in full. That keeps your monthly payment lower, but the balance comes out of your proceeds at that point, so factor it into any future refinance or sale.
Dream For All Runs in Rounds
CalHFA's Dream For All shared appreciation loan offers up to 20% of the price, capped at $150,000, but it opens in funding rounds rather than year-round. The 2026 registration window ran February 24 to March 16, 2026, and it has closed.
Repayment covers the original amount plus a share of the home's appreciation, which makes it a very different trade than MyHome. Watch CalHFA's announcements if you want to be ready for a future round.
The City of Redding Homebuyer Program
The city runs its own silent second loan for income-eligible buyers purchasing inside Redding city limits.
No monthly payments are required, and the maximum loan is $200,000, with the actual amount set by household income, purchase price, first mortgage, and down payment.
You must first qualify for a primary mortgage through an outside lender. You also bring a cash down payment of 3% of the price plus your share of closing costs, and at least half of that down payment has to come from your own assets.
Income and Purchase Price Limits
The maximum purchase price is $374,775. Household income cannot exceed HUD guidelines, which the city publishes as monthly figures by household size, effective June 1, 2026: $4,533 a month for one person, rising to $6,475 for four.
The program is limited to buyers who have not owned a home in the past three years, with limited exceptions the Housing Division can confirm.
Set that cap against the market. Redfin's August 2026 median for Redding was $399,735, so the city program works on homes below the median. It is still a real option, but it narrows the search to the lower-priced part of the city's inventory.
Property Conditions That Rule Homes Out
The home must be owner-occupied, or vacant for at least 90 days, when you make your offer. That rules out a home with tenants in it unless it has already sat empty that long. It must also be inspected by a professional home inspector and by the City.
The city will not accept a purchase contract signed before your eligibility date, so the order matters: get approved for the program, then write offers. Our page on buying a home walks through the rest of the process.
Shasta County's First Time Home Buyer Program
Shasta County Housing and Community Action Programs runs the county version for homes outside Redding city limits. It is a deferred silent second of up to $80,000 for income-qualified buyers who have not owned, or held an ownership interest in, a home in the past three years.
Income limits reach up to 120% of area median income, depending on which funding source is available. The home must appraise at or under $379,000, you contribute at least 3% of the price, and the first and second loans together cannot exceed 97% of appraised value.
How the Interest Adds Up
Unlike MyHome, the county loan can carry up to 3% simple annual interest over a 30-year term. Payments are voluntary and there is no prepayment penalty, but the full principal and accrued interest come due at the end of the term.
The county's own flyer notes that 30 years of interest can add up to 90% of the original principal. On a large county loan, occasional voluntary payments reduce what you owe later.
Homes That Qualify
Existing homes, new construction, condos, and manufactured homes on a permanent foundation are all eligible.
The home must pass an inspection for health and safety standards and local building codes, which matters on older rural properties where additions or systems may not meet current code. On larger parcels, the $379,000 appraisal cap narrows the field quickly.
Requirements That Continue After Closing
The home has to stay in your name and remain your primary residence for the life of the loan. Any change to title, including a sale, triggers repayment of the full balance.
Your homeowners insurance must name the County as an additional mortgagee, and the county verifies that every year. Placing insurance in Shasta County can take longer than buyers expect, so read our breakdown of wildfire insurance in Redding before you budget.
Sequencing a First Purchase in Shasta County
All three programs run through a lender and require homebuyer education, and the local programs want you approved before you shop seriously.
The county's order is a prequalification interview, then a first mortgage, then its own application and a certified homebuyer course, and only then the home search. Getting that order right is most of the work, and more tools are collected on our buyer resources page.
Start With a CalHFA-Approved Lender
A lender that originates CalHFA loans can tell you whether MyHome, a local program, or both fit your income and target price.
Whether a city or county loan can sit alongside MyHome on the same purchase depends on each program's combined loan limits and guidelines, so ask the lender and the program office directly rather than assuming. Budget for the rest of the cash, too.
Our post on closing costs in Redding covers what the county sets and what escrow adds. Working with real estate advisors who know these program rules keeps an accepted offer from falling apart over a vacancy requirement or an inspection item.
Where USDA Fits Outside the Urbanized Area
USDA's guaranteed loan allows no down payment on an eligible property for an eligible household, and CalHFA's USDA first mortgage can be combined with MyHome to help with closing costs.
USDA eligibility follows a mapped boundary, not how rural a property looks, and the Redding urbanized area is excluded. Run the exact address on USDA's eligibility site, check the household income limit with your lender, and ask a real estate agent in Redding, CA to confirm jurisdiction before you get attached to a listing.
Find the Right Program for Your First Shasta County Home
Greater Life Realty helps first-time buyers sort out which programs an address supports before an offer goes in, from inside Redding city limits to Anderson, Shasta Lake City, and the unincorporated county. We can walk you through the order of steps and what each program will ask of the house.
Reach out to us with the areas you are considering and where you are in the lender process. We will help you map the path to your first home, guiding you home to a greater life.
